The core tension: physically growing, structurally stagnant
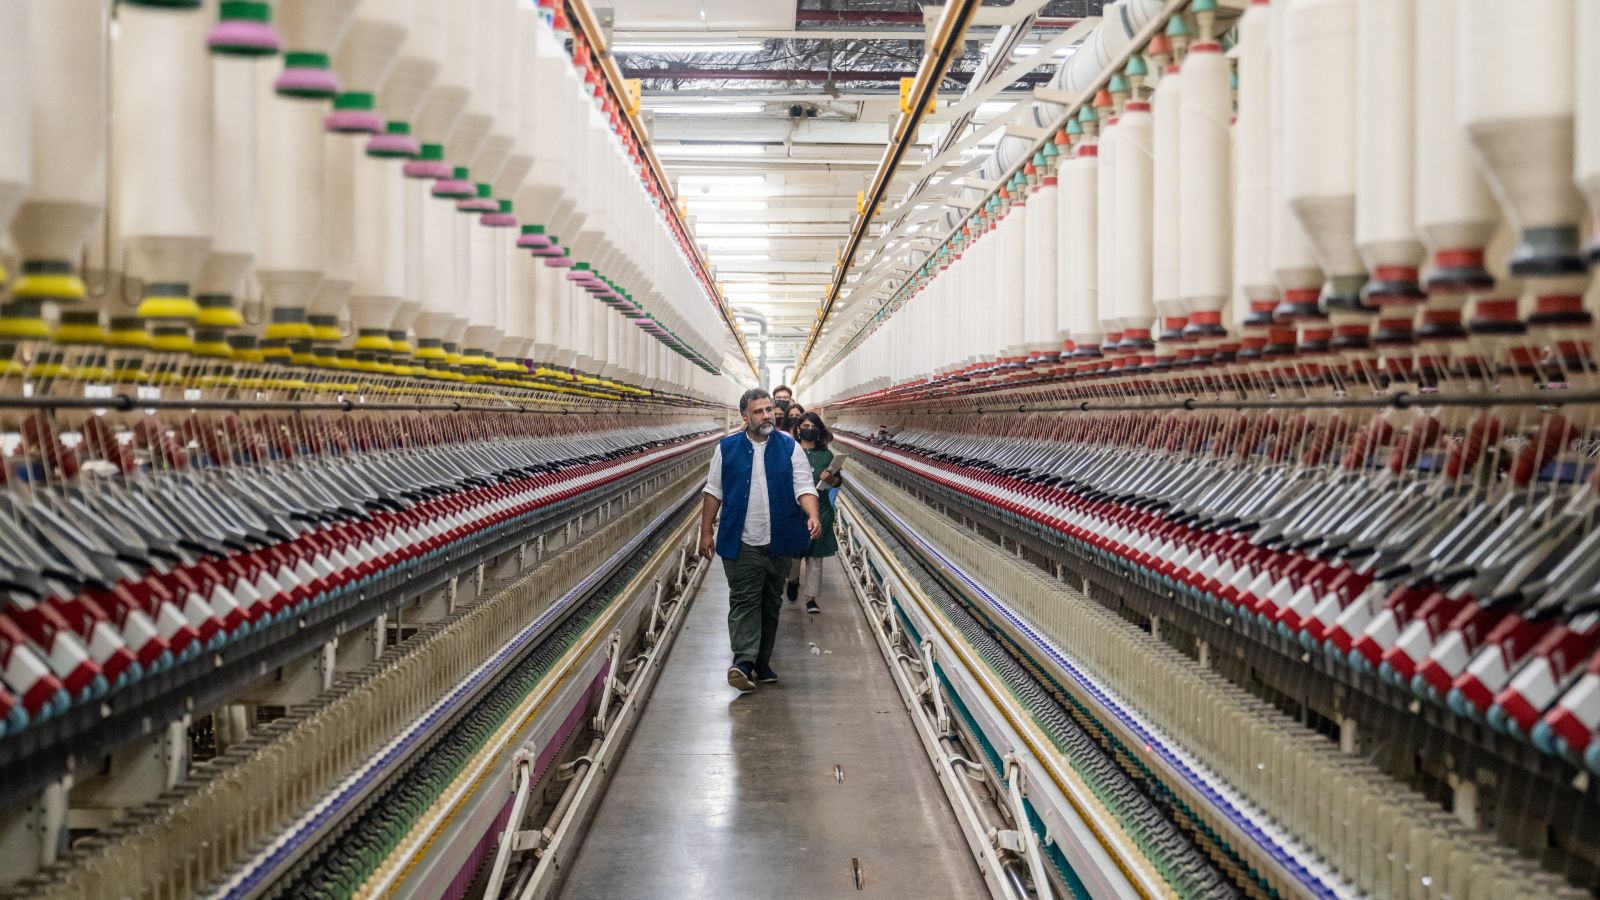
Textiles is not a shrinking sector by the raw counts. Factories grew from 28,600 to 31,176 (2014-15 to 2023-24), workers engaged grew from 2.53M to 3.04M, and GVO rose from ₹4.84 lakh crore to ₹7.81 lakh crore (national ASI totals), a 61% increase, though not on a steady climb: the sector saw a real COVID-year contraction in 2020-21 before a sharp step-up in 2021-22 that has broadly held since. Financial performance of tracked firms has improved. PAT margin flipped from -0.5% (2014-15) to 3.5% (2024-25), ROE from -2.6% to 5.8%, and debt-to-equity nearly halved from 1.95x to 0.65x. Firms also aren't particularly concentrated (HHI 119.2, competitive band) or highly leveraged.
But by the metric that matters most for judging whether a sector is winning, the IIP, Textiles is a structural laggard. It was above the overall manufacturing index every year from 2012-13 to 2016-17, and has been below it every year since. GST disruption to the fragmented powerloom and processing segments, a 24.3% COVID-year output collapse, and sustained competition from Bangladesh and Vietnam in global apparel are the three most-cited reasons. The sector ranks 9th of 10 on IIP level, 9th on growth, 9th on CAGR, and 3rd-most volatile, a combination of consistently underperforming and unusually unstable that few other sectors share.
Trade: a shrinking surplus, not an export success story
Textiles runs a healthy trade surplus (₹2.35 lakh crore in FY24-25) and exports are growing (8.6% YoY, 5.4% five-year CAGR). But imports are growing faster (12.4% YoY, 8.2% five-year CAGR): import dependency is rising, not falling, even in a sector India is traditionally associated with as a global exporter. The US remains the dominant export market by a wide margin (₹92,670 cr vs ₹27,670 cr for #2 Bangladesh), while China dominates the import side (₹30,763 cr, roughly 4x the #2 import partner).
Investment: private-sector-led, but a warning sign in FY24-25
Investment in Textiles is almost entirely private: the Indian private sector dominates new investment overwhelmingly (₹12,507 crore in 2024-25), while combined central and state government investment is negligible. Foreign private investment is small but growing steadily (₹2,900 crore). Dropped-investment count spiked sharply in 2024-25 (69 projects dropped vs 26 in 2022-23) while completed-project count nearly halved (₹7,401 cr to ₹1,252 cr) over the same window. Total outstanding investment stock stood at ₹87,372 crore (233 projects), of which ₹2,712 crore across 16 projects is classified as Implementation Stalled. The PLI scheme carries a total outlay of ₹10,683 crore (~1.4% of GVO), but actual disbursement was just ₹45 crore in 2024-25.
Geography: Tamil Nadu's scale, but not its wage story
Tamil Nadu dominates by every scale measure (23% of national GVO at ₹1,80,991 crore, 28% of employment, most factories) but pays the lowest wages per worker among the top-5 states (₹1,45,501), a labour-intensive, high-volume, lower-cost model. Gujarat (₹1,52,019 crore GVO), Maharashtra (₹71,037 crore), Rajasthan, and Haryana are smaller by scale but 25-50% higher on wages per worker, suggesting a more capital-intensive production mix. The top-5 states account for ~65% of national output: concentrated, but not extreme.
Clusters: six major hubs, aligned with the state geography
Six major Textiles clusters are profiled: Tiruppur (₹44,747 cr exports, FY24-25), Ludhiana (₹15,000 cr turnover, ₹927 cr exports), Surat, Bhiwandi, Pali and Panipat. They cover the sector's best-known hubs and align closely with the state-level geography above.
R&D: a laggard
R&D spend as a share of sales sits at roughly 0.10% throughout the decade, squarely in the "laggard" band (below 1%) with no meaningful trend. This is consistent with Textiles being a labour-intensive, process-driven sector rather than an innovation-intensive one, and shouldn't be read as a failure so much as a structural feature, but it is a real constraint on how the sector can compete against automation-heavy rivals.
Explore the sector: interactive mindmap
Textiles is a sector where the firms are getting healthier and the workforce is growing, but the sector as a whole keeps losing relative ground: output growth lags the rest of manufacturing, and import dependence is rising even as exports grow.
References
Methodological Notes
Institute of Manufacturing and Economy · Sector Snapshots · August 2026 · NIC Divisions 13, 14 · Primary research: Dhairya Shah · Compiled by: Riddhi Bhargava
Author's Profile
Dhairya Shah is a BTech student in Computer Science and Engineering, Class of 2028. He interns at the Institute of Manufacturing and Economy and conducted the primary research for this sector snapshot.